When someone deposits $1,000, nearly 70% of it becomes part of the lending that shapes the real economy:
What your bank does with your money
Most people think a bank account is just storage. But the moment deposits arrive, they become active, flowing into loans that shape neighborhoods, infrastructure, opportunity, and even the environmental conditions people live with.
Banks decide where that money goes next. And those decisions quietly determine:
- who gets to build a home
- which neighborhoods get reliable electricity
- who pays the highest energy bills
- which technologies become affordable
- where small businesses grow
- which communities become resilient to changes
Your money never sits still. The question is what it’s building.
WHERE YOUR
MONEY FLOWS
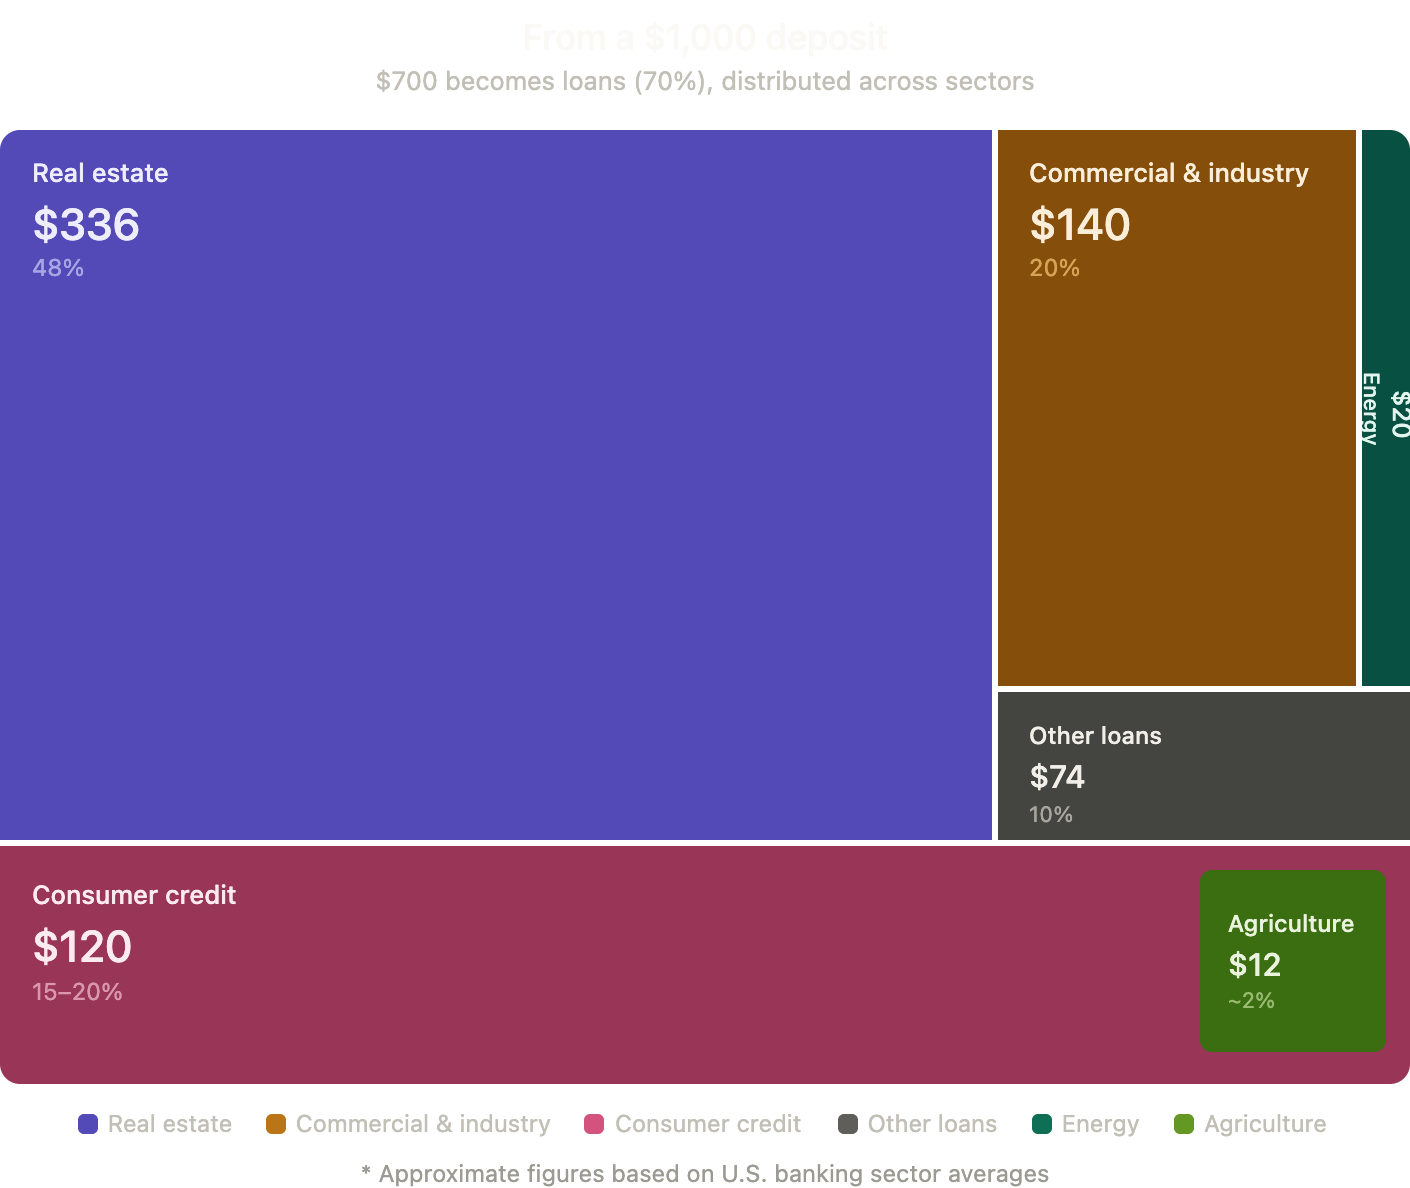
The data presented here is based on the Federal Reserve’s H.8 release and additional reputable sources. Small inconsistencies or rounding differences can occur. The information is provided “as is” for general insight only, without any express or implied guarantees. Please reach out if you notice any material errors, and we’ll make the necessary corrections.
Community Impact
Banks don’t just shape financial outcomes — they shape everyday life in communities. When deposits become loans, those loans turn into buildings, businesses, services, and public spaces.
Lending influences whether:
- small businesses can hire and modernize
- affordable housing includes efficient, healthier systems
- community clinics and essential services can expand
- neighborhoods get the upgrades they need
Strong community lending creates stability, lower costs, and resilience. Weak lending leaves aging buildings, fewer services, and rising household burdens.
INFRASTRUCTURE CHOICES
The infrastructure we live with today — homes, power grids, transit, heating and cooling systems — was financed years ago. Banks influence what gets built next.
Deposits influence whether communities receive:
- grid upgrades that prevent outages
- energy-efficient home improvements
- clean transport options
- modern, low-carbon infrastructure instead of outdated systems
Good financing means reliable, efficient, low-cost systems. Poor financing locks communities into high-cost, high-carbon, unreliable infrastructure for decades.

ACCESS AND OPPORTUNITY
Credit access determines who can participate in the transition to a cleaner, cheaper, more resilient future.
It shapes:
- who can lower bills with efficient upgrades
- which neighborhoods escape high energy burdens
- whose homes can be prepared for heatwaves and storms
- who gets reliable, clean power — and who doesn’t
Communities with limited credit access face higher costs, older systems, and fewer choices. Where deposits flow determines who benefits from modern infrastructure — and who is left behind.
REAL STORIES
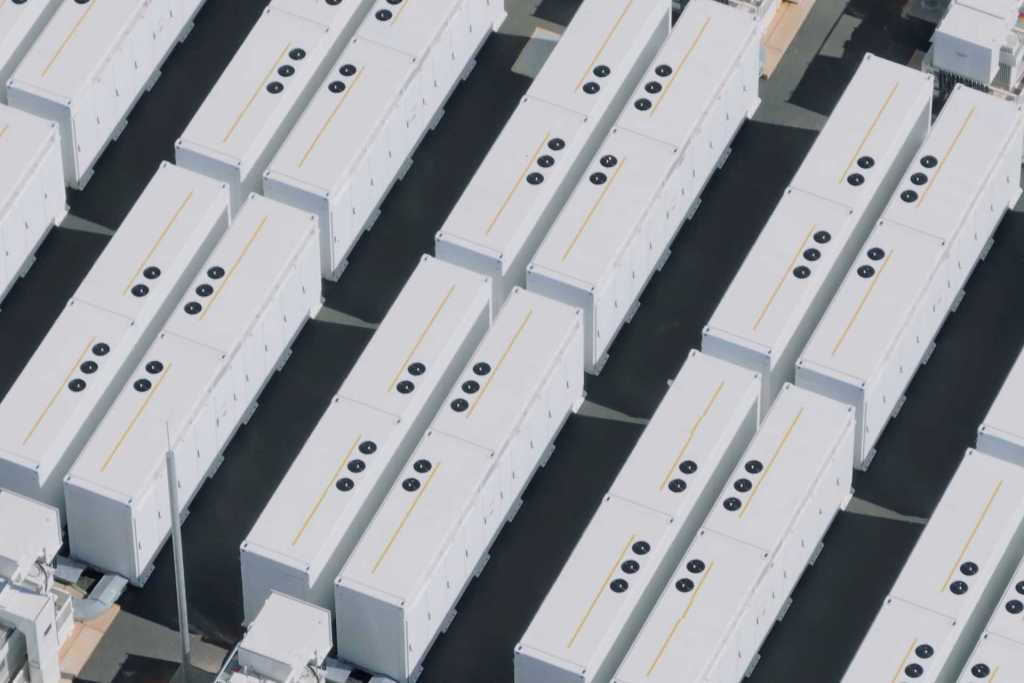
Eastern Shore Battery Storage (Exmore & Tasley, VA)
Financed by Climate First Bank (Florida): Provided funding for two utility-scale battery energy storage systems (total 20 MW power, 80 MWh storage) along Virginia’s Eastern Shore . The project boosts local grid resilience and supports Virginia’s Clean Economy Act goal of 100% clean electricity by 2050 .
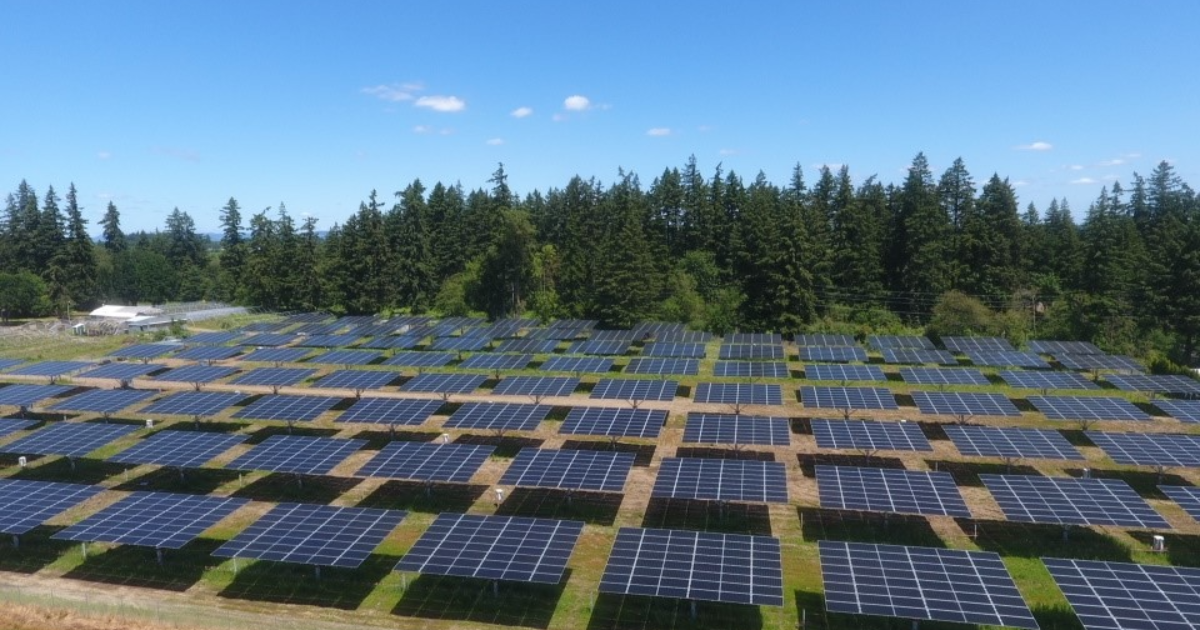
River Valley Community Solar (Woodburn, OR)
Financed by Beneficial State Bank: Supplied a permanent loan to complete a 144-tracker, 3.6 MW community solar farm . The installation provides low-cost solar power to the community – 30% of its output is reserved for low- to moderate-income households at reduced rates , making clean energy accessible to underserved families.
WHAT YOU CAN DO TODAY
You don’t have to switch banks today. The first step is simply seeing what your bank actually does with your money.
Once you understand where your deposits go, choosing what they build next becomes much easier.
Start small:
- Check if your bank is in our tool
- Compare your options in minutes, not hours.
- Use our guides to understand how switching works (and how simple it can be).
- Explore tools like Mighty Deposits to get a fuller picture of your bank’s impact.
That’s why Bank for Good exists — to make the invisible visible and give you the clarity, confidence, and control to choose what your money builds.
Let’s get to work
Every bank, credit union, and financial institution listed on Bank for Good has pledged not to finance fossil fuel extraction or infrastructure.
That’s huge. The more institutions make this promise, and the more people decide to Bank for Good, the closer we are to containing and reversing the climate crisis.
Good financial institutions—get this—actually care about their customers and communities while still offering a range of financial products. Some have branches where you live and tellers who will know your name; others were built entirely online and have top-notch mobile apps and websites.
Many are Minority Depository Institutions, or MDIs, which are owned by, led by, or dedicated to serving people of color. Some are Community Development Financial Institutions (CDFIs): they’re federally recognized and regulated as serving communities that have been shut out of many large financial institutions. And some are members of networks dedicated to doing good while doing business, like B-Corps or the Global Alliance for Banking on Values (GABV). Whatever you’re looking for from your financial institution, you can find it here.
When you start an account with a Bank for Good participating institution, you’re joining a movement of people who are demanding a banking system that puts people before profits. You’re participating in a moment where powerful actors that once seemed invincible are buckling under the power of everyday people. You’re sending a message:
It’s time
to
Bank
for
Good.

